Why Deals Fall Apart Before the Finish Line
Many small business sales that reach the letter of intent stage never close. The reason is rarely the asking price. Deals usually fall apart during due diligence, when a buyer or their lender finds something the owner took for granted. When you prepare to sell a business in Connecticut, Massachusetts, New Jersey, or New York, resolving these five issues early is the difference between a smooth closing and months of negotiation that go nowhere.
This guide explains each deal-killer, how buyers spot it, and what you can do about it before you list. For a broader checklist, see our guide on how to prepare your business for sale.
Deal-Killer #1: Customer Concentration
If one customer accounts for a large share of your revenue, buyers and lenders see risk. Many buyers get uneasy when any single customer represents more than roughly 15% to 20% of annual revenue, because losing that account after the sale could break the numbers the price was built on.
How buyers spot it: a customer revenue breakdown by year, usually requested in the first round of due diligence.
The fix: in the 12 to 24 months before listing, work to diversify your accounts. If that is not possible, secure long-term, transferable service contracts so the incoming owner can see revenue continuity.
Deal-Killer #2: Heavy Owner Dependency
If your business cannot run smoothly for two weeks without you, a buyer is not buying a company, they are buying a job. Buyers want to acquire cash flow, not a 70-hour week.
How buyers spot it: questions about who handles sales, operations, key accounts, and vendor relationships, and what happens when you are away.
The fix: promote a general manager or lead supervisor, document your standard operating procedures, and move day-to-day customer relationships to your team before going to market.
Deal-Killer #3: Commingled or Sloppy Financial Records
Running personal expenses through the business without clear documentation erodes trust. When a buyer’s accountant or lender cannot reconcile your tax returns with your internal profit and loss statements, they will either discount the price or walk away.
How buyers spot it: tax returns, bank statements, and monthly financials that do not tie together.
The fix: work with your accountant and an experienced broker to recast your financials well ahead of time, and document legitimate owner add-backs (SDE) so every dollar of cash flow can be verified. Your advisor can walk you through how each add-back is documented.
Deal-Killer #4: No Documented Growth Story
Buyers pay for future upside, not only past performance. If revenue has flattened or declined in recent periods, expect lower offers unless you can explain why and show a credible path forward.
How buyers spot it: revenue and margin trends by month and year.
The fix: identify two or three realistic growth levers the new owner could pull, such as a new location, commercial contracts, a service line, or digital marketing, and document the evidence behind them.
Deal-Killer #5: Confidentiality Leaks
If employees, customers, or competitors learn the business is for sale before you are ready, the damage can be immediate. Key employees start looking elsewhere, competitors tell customers you are closing, and suppliers tighten credit terms.
How it happens: public listings that name the business, buyers who receive details before a signed agreement, or casual conversations with the wrong person.
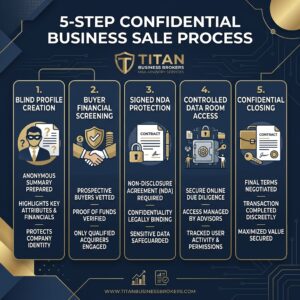
The fix: market the business without naming it, screen buyers before sharing details, and require a signed non-disclosure agreement first. Read more in how confidentiality protects your business during a sale.
A Quick Self-Check Before You List
- Does any one customer represent a large share of revenue?
- Could the business run for two weeks without you?
- Do your tax returns and financial statements tell the same story?
- Can you show where growth will come from?
- Do you have a plan to keep the sale confidential?
Protect Your Exit with Titan Business Brokers
At Titan Business Brokers, we help owners across Connecticut, Massachusetts, New Jersey, and New York find and address these issues before buyers see the numbers. Learn how business brokers help you sell, read about selling a business in Connecticut, or request a confidential valuation call. You can also call (860) 404-9766.
This article is general information, not legal, tax, or financial advice.